Cambodia’s Great Industrial Pivot: Electronics Exports Surge 34% as Non-Garment Manufacturing Hits 62% of All Exports
How electronics, automotive assembly, and solar panel production are rewriting Cambodia’s export identity — and where $5.22 billion in FDI is flowing next
The Numbers That Change Everything
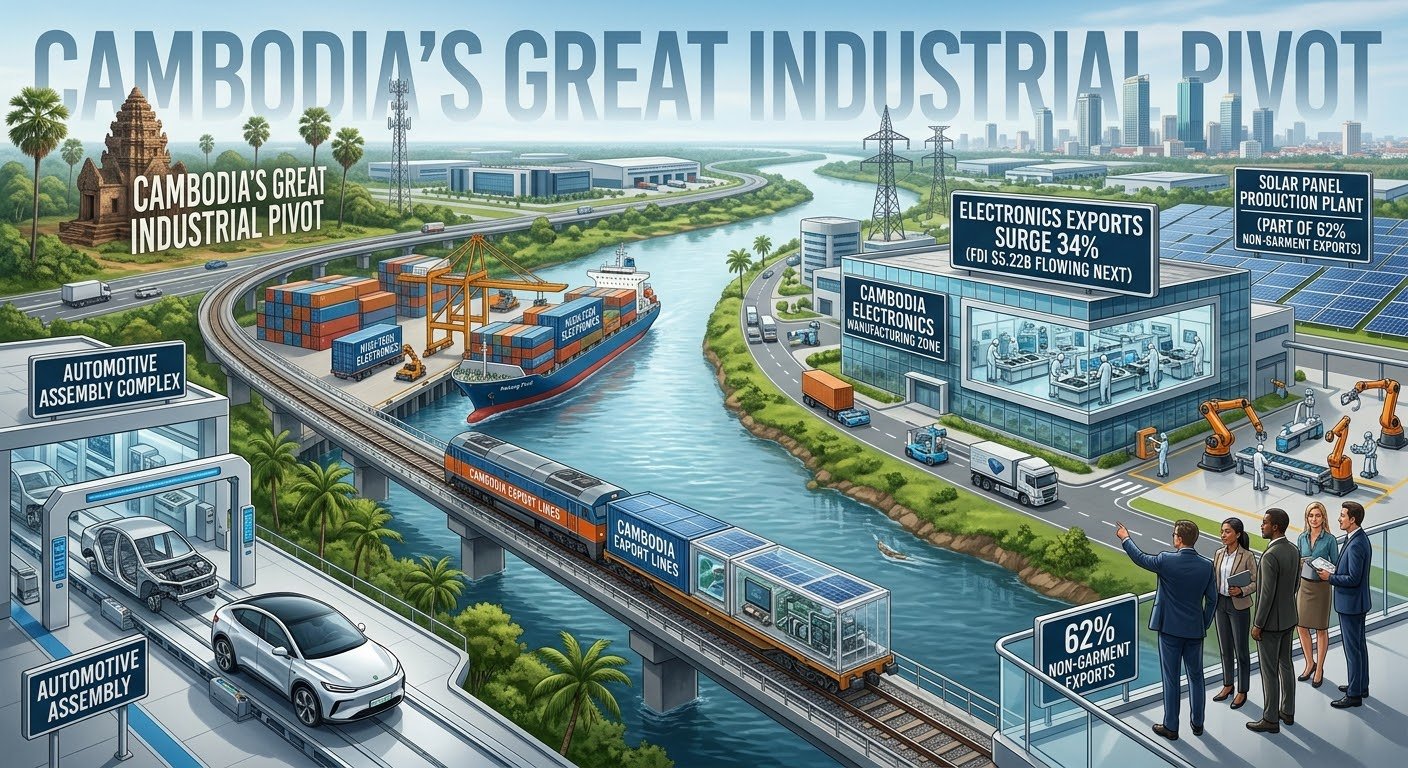
Cambodia’s industrial landscape is undergoing a structural transformation that is difficult to overstate. In the first seven months of 2026, the country exports electrical equipment and electronic components worth $1.05 billion, a 34 percent surge from $781 million during the same period in 2025. This is not a blip. It is an acceleration of a multi-year trend that is fundamentally reshaping what Cambodia makes, sells, and builds. The most striking indicator comes from the overall export composition: non-garment manufacturing goods now account for 62 percent of all Cambodian exports. That figure represents a complete inversion from a decade ago, when garments and footwear commanded 70 percent of total export value. Cambodia is no longer just a garment factory. It is becoming a diversified manufacturing platform for electronics, automotive components, and solar panels, with deep integration into global supply chains stretching from the United States to Japan to the European Union.
From Garments to Circuit Boards: A Decade of Diversification
The shift in Cambodia’s export composition is one of the most dramatic economic transformations in Southeast Asia. Between 2011 and 2015, garments, textiles, and footwear represented roughly 70 percent of Cambodia’s total export value. By the 2020 to 2023 period, that share had contracted to approximately 40 percent. In 2026, non-garment manufacturing goods have surged to 62 percent of total exports. This rebalancing reflects a deliberate government strategy backed by the Special Economic Zone framework, the Qualifying Investment Project (QIP) incentive regime, and Cambodia’s participation in the Regional Comprehensive Economic Partnership (RCEP). The result is a manufacturing sector that now spans electronics assembly, automotive parts production, solar panel manufacturing, and upstream textile inputs like yarns and fabrics. The garment sector itself is evolving: $1.1 billion in foreign direct investment flows into textiles and garments in the first half of 2026 alone, but the investment is moving upstream into yarns and textiles rather than traditional cut-make-trim operations. This vertical integration strengthens the entire industrial ecosystem and creates higher-value jobs.
| Period | Garment Share | Non-Garment Mfg Share | Total Exports |
|---|---|---|---|
| 2011-2015 | 70% | 30% | $12-15B (est.) |
| 2016-2019 | 55% | 45% | $20-25B (est.) |
| 2020-2023 | 40% | 60% | $22-28B |
| 2025 (full year) | ~38% | ~62% | $38.7B |
| H1 2026 | ~35% | ~65% | $17.2B |
| Jan-Jul 2026 | ~34% | ~66% | $20.81B |
Electronics: The $1.05 Billion Rocket
Electrical equipment and electronic components represent the single most dynamic export category in Cambodia’s portfolio. The $1.05 billion exported in the first seven months of 2026 places the sector on track to surpass $1.8 billion for the full year, potentially exceeding the $2.71 billion record set in 2024. The United States is the dominant destination, absorbing $1.63 billion in Cambodian electronics and electrical exports in 2024 alone. Japan ($217 million) and Thailand ($179 million) follow as the second and third largest markets respectively. This geographic diversification is a strategic asset. Cambodia’s electronics exports include wiring harnesses, circuit board assemblies, consumer electronic components, and industrial electrical equipment. The growth is driven by a combination of competitive labor costs, SEZ-based manufacturing infrastructure, and Cambodia’s tariff advantages under RCEP and the US-Cambodia Reciprocal Trade Agreement. At the Cambodia Industrial Development Conference and Expo in July 2026, 162 companies participated, including 36 from China and 118 operating in Cambodia, signaling deepening international engagement in the country’s industrial sector.
Automotive: 11 Plants, $2.79 Billion Invested
Cambodia’s automotive sector is one of the most surprising investment stories in Southeast Asia. As of July 2026, the country hosts 11 vehicle manufacturing, assembly, and production facilities with a combined annual production capacity of approximately 37,900 vehicles. Cumulative investment in the sector reaches $2.79 billion, with exports valued at around $1.14 billion. More than 173,000 vehicles have been exported from Cambodian factories to date. The sector is expanding rapidly. TH Automotive Manufacturing is set to inaugurate a new vehicle assembly plant, and the CDC has approved a LYNK and CO assembly facility. A $450 million tyre manufacturing factory is expected to create 3,000 additional jobs. The product mix now includes passenger cars, trucks, buses, and electric vehicles. Cambodia’s automotive ambitions are supported by its strategic location, access to ASEAN markets through RCEP, and significantly lower production costs compared to Thailand and Vietnam. The CDC identifies automotive as a priority sector, offering the full QIP incentive package including tax holidays of up to nine years. For investors, this sector offers exposure to both the regional ASEAN automotive supply chain and the growing domestic market of 17 million consumers with rising purchasing power.
Key Automotive Milestones
The automotive sector’s rapid growth reflects a deliberate industrial policy. The CDC classifies automotive components as a priority investment sector, which unlocks a comprehensive incentive package. Existing assembly operations produce brands ranging from Chinese manufacturers to regional brands, with the recent approval of LYNK and CO marking the entry of a major global nameplate. The $450 million tyre factory represents the kind of upstream investment that deepens the supply chain and reduces import dependency. With 11 plants operational or under construction, Cambodia is building the critical mass needed to attract Tier 1 and Tier 2 component suppliers, creating a self-reinforcing investment cycle.
Solar Panel Export Juggernaut: 45 Factories, $2.4 Billion Peak
Cambodia’s solar panel manufacturing sector is a remarkable success story that receives surprisingly little international attention. At its peak in 2023, Cambodia exported solar panels worth $2.4 billion, making them the country’s most significant non-textile export product. This represents a staggering 2.8-fold increase from 2022, when solar panel exports reached $1.0 billion. Currently, 45 factories are producing solar panels across the country, primarily in SEZs. The sector benefits from Cambodia’s high solar irradiance, competitive manufacturing costs, and access to the US market. However, the sector faces headwinds. US trade investigations into solar module imports from Southeast Asia, including Cambodia, create uncertainty. The US initially imposed tariffs as high as 145% on Chinese-origin solar panels routed through ASEAN countries, though these were subsequently reduced. Cambodia’s solar panel industry is at a strategic inflection point: the factories and expertise are in place, but the trade policy environment requires careful navigation. For investors, the sector offers two distinct opportunities: first, manufacturing solar components for non-US markets including Japan, the EU, and ASEAN; and second, investing in Cambodia’s domestic solar energy infrastructure, which currently generates less than 10 percent of the country’s electricity despite having one of the highest solar irradiance levels in the region.
Upstream Shift: $1.1 Billion Flows Into Yarns and Textiles
The garment sector is not dying. It is evolving. In the first half of 2026, foreign direct investment in the textile and garment industry reaches $1.1 billion, according to the Textile, Apparel, Footwear and Travel Goods Association (TAFTAC). Critically, the investment is flowing upstream into yarns and textiles rather than traditional cut-make-trim garment assembly. This vertical diversification strengthens Cambodia’s position in the global textile value chain and reduces dependency on imported raw materials. Cambodia’s garment, textile, and footwear exports reach $7.97 billion in the first nine months of 2026, up 13.18 percent year-on-year. For the full year 2025, GTF exports top $16 billion. The Cambodia Textile Summit 2026 highlights the industry’s commitment to sustainability and innovation as global competition intensifies. For investors, the upstream shift creates opportunities in spinning, weaving, dyeing, and fabric finishing operations that serve both the domestic garment sector and regional export markets. These operations typically require higher capital investment but generate stronger margins and more stable revenue than cut-make-trim assembly.
The SEZ Engine: 9-Year Tax Holidays and 19 Priority Sectors
Cambodia’s Special Economic Zone framework is the structural backbone of the industrial diversification story. The country hosts 56 SEZs, of which 33 are operational. Investors in SEZs receive a comprehensive incentive package that includes profit tax exemption for up to nine years, import duty exemption on construction equipment and raw materials, VAT incentives, and streamlined customs procedures. The CDC identifies 19 sectors and activities as entitled to investment incentives, with electrical and electronic industries, automotive components, and special economic zones themselves among the designated priority sectors. The QIP regime extends these benefits beyond SEZ boundaries, allowing qualifying investments anywhere in Cambodia to access similar tax advantages. This policy architecture is specifically designed to attract the kind of higher-value manufacturing that drives the electronics, automotive, and solar panel sectors. For an electronics assembly operation, the combination of a nine-year tax holiday, duty-free import of components, and a $210 per month minimum wage creates a cost structure that is difficult to match anywhere in the ASEAN region.
Trade Architecture: RCEP, US Reciprocal Deal, and Tariff Clarity
Cambodia’s trade policy framework provides a dual advantage for manufacturers. Under the Regional Comprehensive Economic Partnership (RCEP), Cambodian-made products enjoy preferential tariff access to 14 other Asia-Pacific economies, including China, Japan, South Korea, Australia, and New Zealand. This is particularly valuable for electronics and automotive component manufacturers who rely on regional supply chains. The US-Cambodia Reciprocal Trade Agreement, finalized in October 2025, provides additional structure. The United States maintains a 19 percent reciprocal tariff rate on Cambodian goods, while Cambodia has eliminated tariffs on 100 percent of US products. The CDC has clarified that a new 10 percent US tariff announced in July 2026 is not cumulative with the existing 19 percent rate, providing important clarity for exporters. Cambodia’s zero-tariff commitment on US goods also creates opportunities for American machinery and technology imports that support the industrial upgrade. For electronics investors, the trade architecture means duty-free access to the world’s largest consumer electronics market (US) and preferential access to the world’s largest manufacturing supply chains (RCEP). This dual-market positioning is a genuinely rare competitive advantage.
| Trade Framework | Key Benefit | Impact on Electronics |
|---|---|---|
| RCEP | Preferential tariffs to 14 Asia-Pacific economies | Regional supply chain integration |
| US Reciprocal Deal | 19% tariff (stable, non-cumulative) | $1.63B electronics to US in 2024 |
| QIP/SEZ Incentives | 9-year tax holiday + duty-free imports | Lower landed cost vs peers |
| Zero US Tariff on Imports | No duty on US machinery/tech | Easier factory setup and upgrades |
Labor Cost Advantage: $210 Per Month in a High-Skill Transition
Cambodia’s manufacturing labor costs remain among the most competitive in Southeast Asia. The 2026 minimum wage for the textile, garment, and footwear sector is $210 per month ($208 for probationary workers). This rate is significantly below China, Thailand, and Indonesia, and is roughly on par with Vietnam’s Region I wage. However, the more important metric for electronics and automotive investors is total labor cost including benefits, social security, and overtime, which in Cambodia remains substantially lower than in neighboring countries. As of June 2026, Cambodia’s 3,319 large-scale operating factories collectively employ more than 1.3 million workers. The workforce is young, with a median age below 27, and increasingly adaptable to electronics assembly and automotive component manufacturing. The government and private sector are investing in technical and vocational education to support the skills transition. For investors evaluating manufacturing locations, the combination of low labor costs, a young workforce, and improving technical skills creates a compelling value proposition for electronics assembly, quality control, and light manufacturing operations that do not require the deep engineering talent pools of Malaysia or Singapore but still demand reliable, trainable production workers.
| Sector | Investment (Cumulative) | Exports (Annual/Latest) | Key Metric |
|---|---|---|---|
| Electronics & E&E | $3.5B+ (est.) | $1.05B (Jan-Jul 2026) | +34% YoY growth |
| Automotive | $2.79B | $1.14B | 11 plants, 37,900 capacity |
| Solar Panels | $2B+ (est.) | $2.4B (2023 peak) | 45 factories |
| Garment/Textile/Footwear | $12B+ (est.) | $16B (2025 full year) | $1.1B H1 2026 FDI |
| Total Exports | — | $20.81B (Jan-Jul 2026) | +21.3% YoY |
Investment Playbook: Where Smart Money Is Going
The data points to four high-conviction investment opportunities in Cambodia’s industrial diversification. First, electronics assembly and component manufacturing offers the strongest growth trajectory, with 34 percent export growth and direct access to the US market. The optimal entry point is through an SEZ-based QIP, which unlocks the full incentive package. Second, automotive component supply is an early-stage opportunity with first-mover advantages. As the 11 assembly plants scale production, demand for local Tier 2 and Tier 3 component suppliers is increasing. Third, solar panel manufacturing for non-US markets offers established infrastructure with 45 factories already operational and growing demand from Japan, the EU, and ASEAN. Fourth, upstream textile operations including spinning, weaving, and dyeing serve the massive $16 billion garment export sector while generating higher margins than assembly. The common thread across all four opportunities is Cambodia’s structural cost advantage, the SEZ/QIP incentive framework, and improving trade access through RCEP and the US reciprocal deal. The risks include US tariff uncertainty, limited domestic supplier depth, and infrastructure gaps outside major SEZs. However, the reward profile, particularly for investors who enter during this early diversification phase, is compelling. Cambodia’s industrial pivot is real, it is accelerating, and the data increasingly supports the investment thesis.
Four High-Conviction Opportunities
- Electronics Assembly: $1.05B and growing at 34%. SEZ-based QIP for maximum incentives. US market access under 19% tariff.
- Automotive Components: $2.79B invested, 11 plants scaling. First-mover advantage for Tier 2/3 suppliers. RCEP market access.
- Solar Manufacturing for Non-US Markets: 45 factories operational. $2.4B peak export. Diversify to Japan, EU, ASEAN to mitigate US tariff risk.
- Upstream Textiles: $1.1B FDI flowing into yarns and fabrics. Higher margins than cut-make-trim. Serves $16B garment export base.